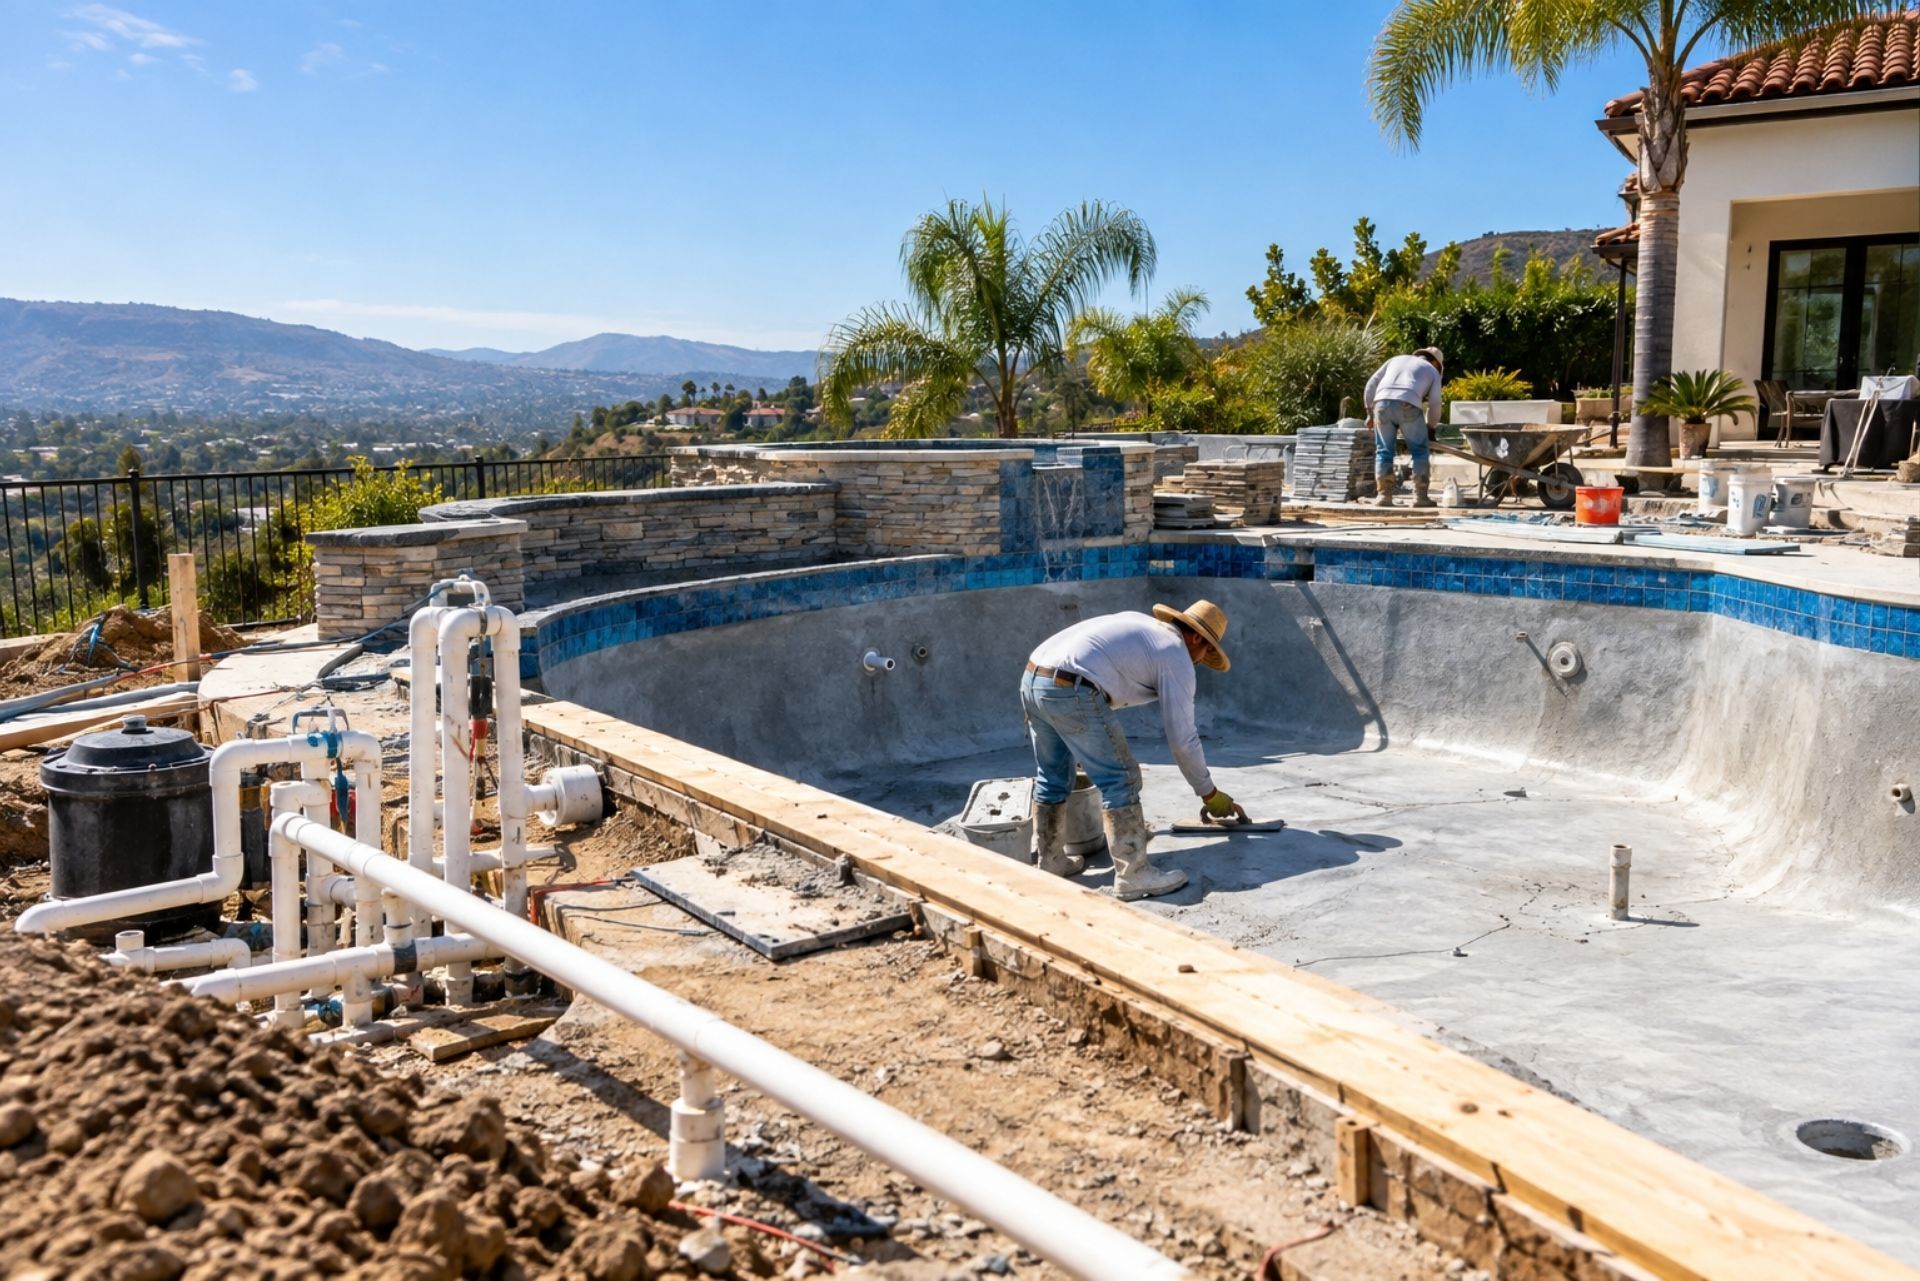
Building a swimming pool in California involves a unique combination of risks you won't find in most other trades. Between
excavation near underground utilities, hydrostatic pressure failures, chemical handling, and the state's aggressive construction defect laws, the
insurance needs of a C-53 contractor are genuinely complex. A single cracked pool shell or a backhoe strike on a gas line can generate claims that dwarf the cost of the pool itself. If you're operating as a swimming pool contractor in California, understanding the full spectrum of coverage you need - from general liability and workers' comp to CSLB bonds and completed operations - isn't optional. It's the difference between running a sustainable business and gambling with your livelihood. This guide breaks down each type of coverage, explains the state-specific requirements that make California different, and offers practical strategies for keeping premiums manageable without leaving dangerous gaps.
Core Liability Risks for California Pool Builders
Pool construction sits at the intersection of heavy equipment work, structural engineering, plumbing, and electrical installation. That overlap creates exposure on multiple fronts. A standard general contractor policy often excludes or undercovers the specific risks pool builders face, which is why specialized coverage matters so much in this trade.
General Liability and Property Damage Claims
General liability insurance is the foundation of any pool contractor's risk management. It covers third-party bodily injury and property damage: think a homeowner's child tripping over materials on the job site, or your crew damaging a neighbor's retaining wall during excavation. For California pool contractors, property damage claims are particularly common because most pools are built in established residential neighborhoods with underground utilities, irrigation systems, and mature landscaping in close proximity.
A typical general liability policy for a C-53 contractor provides coverage for $1 million per occurrence and $2 million aggregate, though rates vary significantly based on your claims history, revenue, and the types of pools you build. If you're doing gunite or shotcrete work, expect higher premiums than a vinyl liner installer. Your claims history follows you through industry databases, and even a single large claim can increase your rates for three to five years.
Professional Liability for Design and Engineering Errors
Many pool contractors handle some degree of design work, whether it's drafting pool layouts, specifying equipment, or engineering retaining walls around hillside installations. If a design flaw causes structural failure or drainage problems, your general liability policy likely won't cover it. Professional liability (errors and omissions) insurance fills that gap.
California's 10-year statute of repose for latent construction defects means a
structural pool shell failure or underground leak can generate claims up to a decade after you finished the job. That's a long tail of exposure. If you're providing any design services, even informally, a professional liability policy is worth the investment. General professional liability (E&O) for small businesses in 2026 averages approximately $675 per year (https://www.moneygeek.com/insurance/business/professional-liability/cost/), though specialized design-build policies for high-volume pool architects can reach the $1,200+ range (https://www.wexfordins.com/post/how-much-does-business-insurance-cost-for-a-swimming-pool-contractor).
By: Patrick Caruso
President of Caruso Insurance Services
State-Mandated Coverage and CSLB Requirements
California imposes specific insurance and bonding requirements on licensed contractors, and the rules for pool builders have been shifting. Getting this wrong can cost you your license.
California Contractor License Bonds
Every C-53 swimming pool contractor must carry a contractor license bond of $25,000, filed with the Contractors State License Board (https://wpisgroup.com/california-workers-compensation-guide). This bond protects consumers if you fail to perform contracted work, violate building codes, or commit fraud. It's not insurance for you: it's a financial guarantee for your customers, and if a claim is paid against it, you owe the bonding company back.
Beyond the license bond, you may need to post a qualifying individual bond if you're acting as the responsible managing employee for another company's license. Some municipalities also require separate performance bonds for larger projects, particularly commercial pool installations or public aquatic facilities.
Workers' Compensation Laws for Pool Construction Crews
Workers' comp is where California pool contractors need to pay close attention to evolving regulations. The universal workers' compensation mandate for all California contractors has been delayed to January 1, 2028, by Senate Bill 1455. Until then, C-53 contractors who do not have employees are still permitted to file a certificate of exemption for workers' compensation insurance.
If you have even one employee, however, workers' comp is already mandatory with no exceptions. Pool construction carries high classification rates because of the physical nature of the work: heavy equipment operation, trenching, working with rebar, and exposure to chemicals. The WCIRB's September 2026 advisory rates note that while overall system costs have stabilized,
cumulative trauma claim frequency remains elevated, which keeps premiums firm for construction trades. Budget roughly $8.00 to $13.00 per $100 of payroll depending on your specific classification codes and experience modification rate (https://brightcoastins.com/workers-comp-codes/ca/5213).
Specialized Endorsements for the Swimming Pool Industry
Standard commercial policies are built for general contractors. Pool builders need endorsements that address the specific ways pools fail.
Swimming Pool Pop-up and Hydrostatic Pressure Coverage
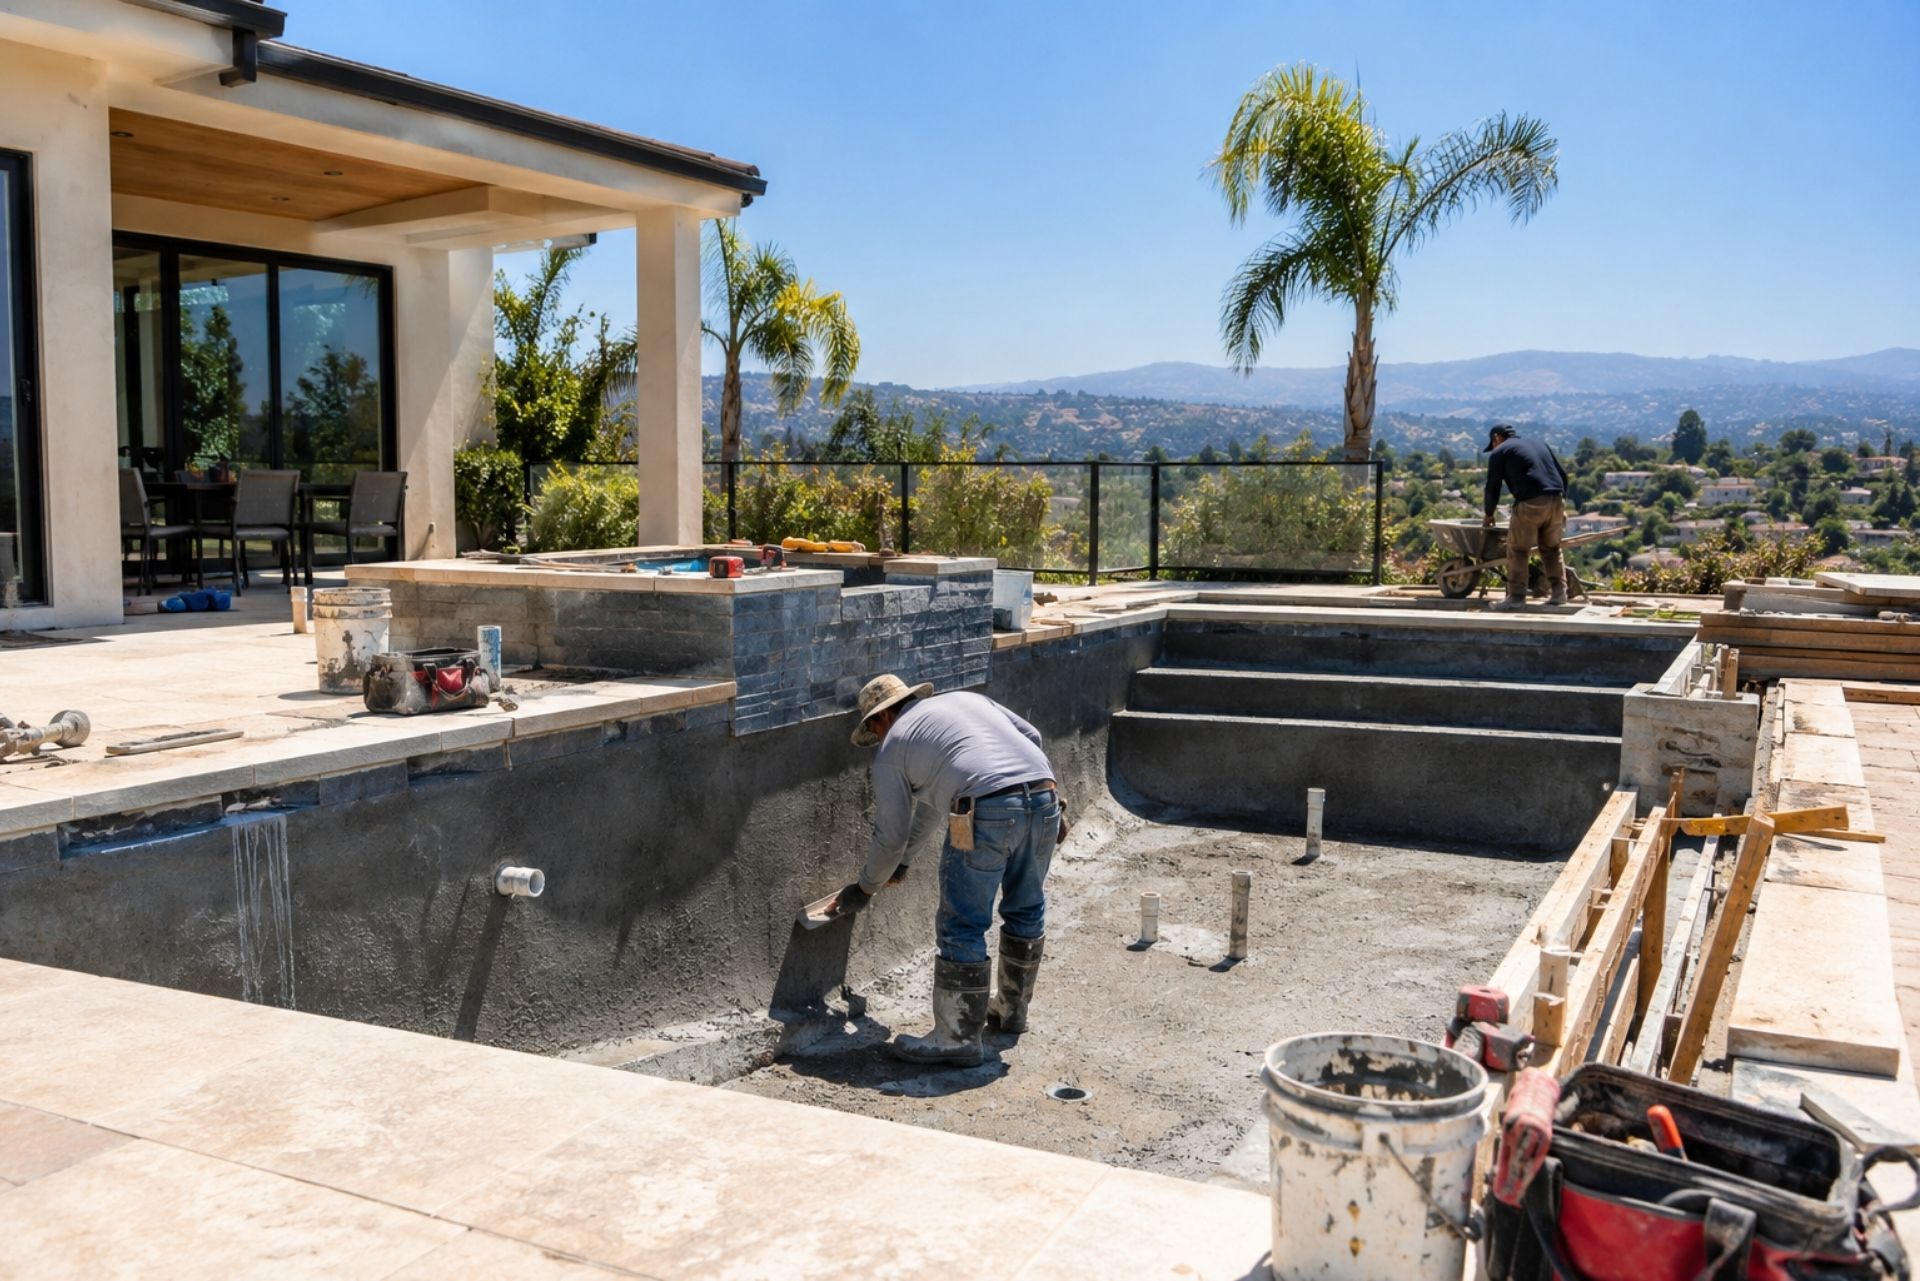
When groundwater levels rise, an empty pool can literally pop out of the ground. This phenomenon, called pool pop-up, is more common than most homeowners realize, especially in areas with high water tables or after heavy rain seasons. Standard general liability policies often exclude hydrostatic pressure damage. A specific endorsement covers the cost of resetting the pool, repairing surrounding structures, and addressing any resulting property damage.
If you work in coastal areas, flood-prone valleys, or anywhere with seasonal water table fluctuations, this endorsement is essential. The cost is relatively modest: usually a few hundred dollars added to your annual premium (https://www.reddit.com/r/Insurance/comments/1509vro/hydrostatic_pressure_endorsement/).
Faulty Workmanship and Product Completed Operations
Completed operations coverage protects you after you've finished a project and moved on. If a pool develops cracks, leaks, or equipment failures due to workmanship issues, this is the coverage that responds. California's SB 800 Right to Repair Act creates a specific pre-litigation framework for residential construction defects: homeowners must provide a formal notice of defect to the contractor, who then has 14 days to acknowledge the claim and 30 days post-inspection to offer a repair.
This process means your completed operations coverage will be triggered regularly, not just in extreme cases. Make sure your policy doesn't sunset completed operations coverage after a short period. Given California's 10-year statute of repose, you need coverage that extends well beyond project completion. Some carriers offer tail coverage or extended reporting periods specifically for this purpose.
Pollution Liability for Pool Chemicals and Runoff
Pool contractors handle muriatic acid, chlorine, and other chemicals that can cause serious environmental damage if spilled or improperly discharged. Standard general liability policies almost universally exclude pollution events. A pollution liability endorsement or standalone policy covers cleanup costs, third-party bodily injury from chemical exposure, and regulatory fines.
This is especially important in California, where environmental enforcement is aggressive. A chemical spill that reaches a storm drain can trigger response from multiple agencies and generate six-figure cleanup costs. Pollution liability coverage is available for small to mid-size pool contractors to address these specific environmental risks.
Protecting Physical Assets and Equipment
Your tools, equipment, and vehicles represent significant capital investment. Protecting them requires coverage beyond a standard property policy.
Inland Marine Insurance for Excavators and Tools
Inland marine insurance covers equipment and tools in transit and at job sites. For pool contractors, this means excavators, compactors, plaster rigs, rebar benders, and the array of specialized tools that make pool construction possible. A single mini-excavator represents a significant capital investment, and standard commercial property insurance typically only covers equipment at your listed business location, not at a customer's home.
Inland marine policies can be written on a scheduled basis (listing specific high-value items) or as a blanket policy covering all equipment up to a stated limit. Scheduled coverage is generally cheaper if you have a few high-value pieces, while blanket coverage works better for contractors with large tool inventories that change frequently.
Commercial Auto Insurance for Service Fleets
Pool contractors rely heavily on trucks, trailers, and service vans. California requires minimum auto liability limits, but those minimums are dangerously low for commercial operations. A truck towing a trailer loaded with an excavator that causes a multi-vehicle accident can easily generate claims exceeding $500,000. Consider carrying higher liability limits and a commercial umbrella policy that extends over both your auto and general liability.
Hired and non-owned auto coverage is also important if employees ever use personal vehicles for work purposes, even just running to a supply house.
Managing Subcontractor Risks and Certificates of Insurance
Most pool projects involve subcontractors for electrical, plumbing, decking, or landscaping work. Every uninsured or underinsured sub is a liability sitting on your job site. If a sub's employee gets hurt and the sub doesn't carry workers' comp, the claim flows uphill to you as the general contractor.
Require certificates of insurance from every subcontractor before they set foot on your project. Verify that their general liability and workers' comp policies are active and that you're listed as an additional insured on their general liability policy. This isn't bureaucratic overkill: it's the single most effective way to prevent claims from landing on your policy. Keep certificates on file and track expiration dates. A lapsed policy does you no good when a claim shows up six months later.
Written subcontractor agreements should include hold-harmless and indemnification clauses that shift liability for the sub's own negligence back to them. Have an attorney review your template agreement. The few hundred dollars this costs is trivial compared to the exposure of operating without one.
California insurance premiums for construction trades are among the highest in the country. But there are legitimate ways to bring costs down without sacrificing critical coverage.
Implementing Safety Protocols and OSHA Compliance
Your experience modification rate (EMR) is the single biggest lever you have on workers' comp premiums. An EMR below 1.0 means you're safer than average and earns you a discount; above 1.0 means you're paying a surcharge. Reducing workplace injuries through documented safety programs, regular toolbox talks, proper equipment maintenance, and OSHA compliance training directly lowers your EMR over time.
Invest in trench safety equipment, enforce hard hat and high-visibility vest requirements, and conduct pre-dig utility locates on every single project. These aren't just good practices: they're premium reducers.
Bundling Policies and Risk Retention Options
Purchasing multiple policies from a single carrier often qualifies you for package discounts of 10% to 20%. A business owner's policy (BOP) that bundles general liability with commercial property coverage is a common starting point, though pool contractors typically need to add endorsements that a basic BOP doesn't include.
Higher deductibles can also lower premiums significantly. If you can absorb $5,000 or $10,000 on a property claim without financial strain, opting for a higher deductible reduces your annual premium while keeping catastrophic coverage in place. Just make sure you actually have that deductible amount accessible: choosing a deductible you can't afford defeats the purpose.
Building a Durable Insurance Program
Running a pool construction business in California without proper insurance coverage for general liability, excavation risks, workers' comp, CSLB bonds, and completed operations is a risk no contractor should take. The state's regulatory environment, long defect liability windows, and high claim costs make comprehensive coverage a business necessity rather than a nice-to-have.
Review your policies annually, especially as your revenue grows or you add new service types. Work with a broker who specializes in construction trades and understands the specific endorsements pool contractors need. The workers' comp mandate changes coming in 2028 will affect every C-53 licensee, so start planning now if you currently operate under an exemption. A well-structured insurance program doesn't just protect you from catastrophic loss: it makes you more competitive, because savvy homeowners and general contractors increasingly verify coverage before awarding contracts.
ABOUT THE AUTHOR:
PATRICK CARUSO
I’m Patrick Caruso, founder of Caruso Insurance, and I have spent more than 25 years helping families, contractors, and small businesses across Southern California make confident insurance decisions. I focus on explaining coverage in clear terms, comparing multiple carriers, and supporting clients with steady communication so they feel secure with each step. My goal is to provide dependable guidance, simple answers, and a smooth process for anyone who needs personal or business insurance.
Contact Us
Service that stays with you.
Our team helps simplify insurance decisions for families and businesses. We focus on clear explanations, fast responses, and dependable service. You can count on us for help with coverage questions, updates, and long-term support.
Coverage that keeps you secure
Reliable Protection for Everyday Life
Home insurance helps protect your house, personal belongings, and liability risks. We explain coverage options clearly so you know what your policy includes.
Auto insurance provides protection for accidents, liability, and vehicle damage. We help you compare options so you can choose coverage that fits your driving needs.
Motorcycle insurance provides coverage for riders and their bikes. We help you select options that match how and where you ride.
RV insurance supports protection for motorhomes and recreational vehicles. Coverage applies during travel and while parked.
Coverage Built for Contractors and Trades
Support that keeps your work moving.
General Liability Insurance
General liability insurance helps protect contractors from injury and property damage claims. It supports jobsite requirements and contracts.
Workers Compensation
Workers compensation insurance helps protect employees injured while working. It also supports compliance with state requirements.
Commercial Auto Insurance
Commercial auto insurance provides coverage for work vehicles used on jobsites. It helps protect drivers and company vehicles.
Contractor Insurance
Contractor insurance supports trades and service professionals across Southern California. It helps protect tools, equipment, and daily operations.
Cyber Liability Insurance
Cyber liability insurance helps protect business data and customer information. It supports recovery from digital incidents.
Commercial Property Insurance
Commercial property insurance helps protect offices, shops, and equipment. It supports recovery after covered damage.
Coverage Built for Specialized Work
Support for high-risk and service-driven industries.
Simple Steps Supported by Steady Guidance
A Clear Path to Coverage
Trusted by Clients Across Southern California
Clear service backed by real experiences.
Answers to Common Questions.
Clear explanations to guide your decisions.
How do I know which insurance policy is right for me?
We compare coverage options from multiple carriers to help you see differences in protection and price. You can review clear details and ask questions so you understand what each policy covers. Our team guides you step by step so you feel sure about your decision.
What factors affect my auto insurance premium?
Auto insurance premiums are influenced by your driving history, age, location, vehicle type, and coverage choices. A clean driving record and good safety features can help lower costs. We review these factors with you and help find coverage that fits your budget and needs.
Does homeowners insurance cover all types of damage?
Standard homeowners insurance protects your structure, personal belongings, liability, and additional living expenses in many cases. However, it usually does not include flood or earthquake damage without separate policies. We help you decide if extra coverage is right for your home and location.
Can I update my policy or get certificates online?
Yes. You can submit requests for policy changes and certificates through our online service form at any time. Our team processes those requests quickly and confirms updates once complete so you have the documents you need.
Do I need separate insurance for business risks like EPLI or E&O?
Yes. General liability and workers compensation cover many business risks but do not protect against all exposures. For example, Employment Practices Liability Insurance (EPLI) covers claims like wrongful termination or discrimination, and Errors & Omissions (E&O) covers claims based on mistakes in professional services. We help you identify which extra policies your business may need.
What happens if I need to file a claim?
If you need to file a claim, we guide you through the process and help you contact the insurance carrier. We explain what information you should provide, answer your questions, and stay available while the carrier reviews your claim. This support helps you move forward with confidence.
Contact Us