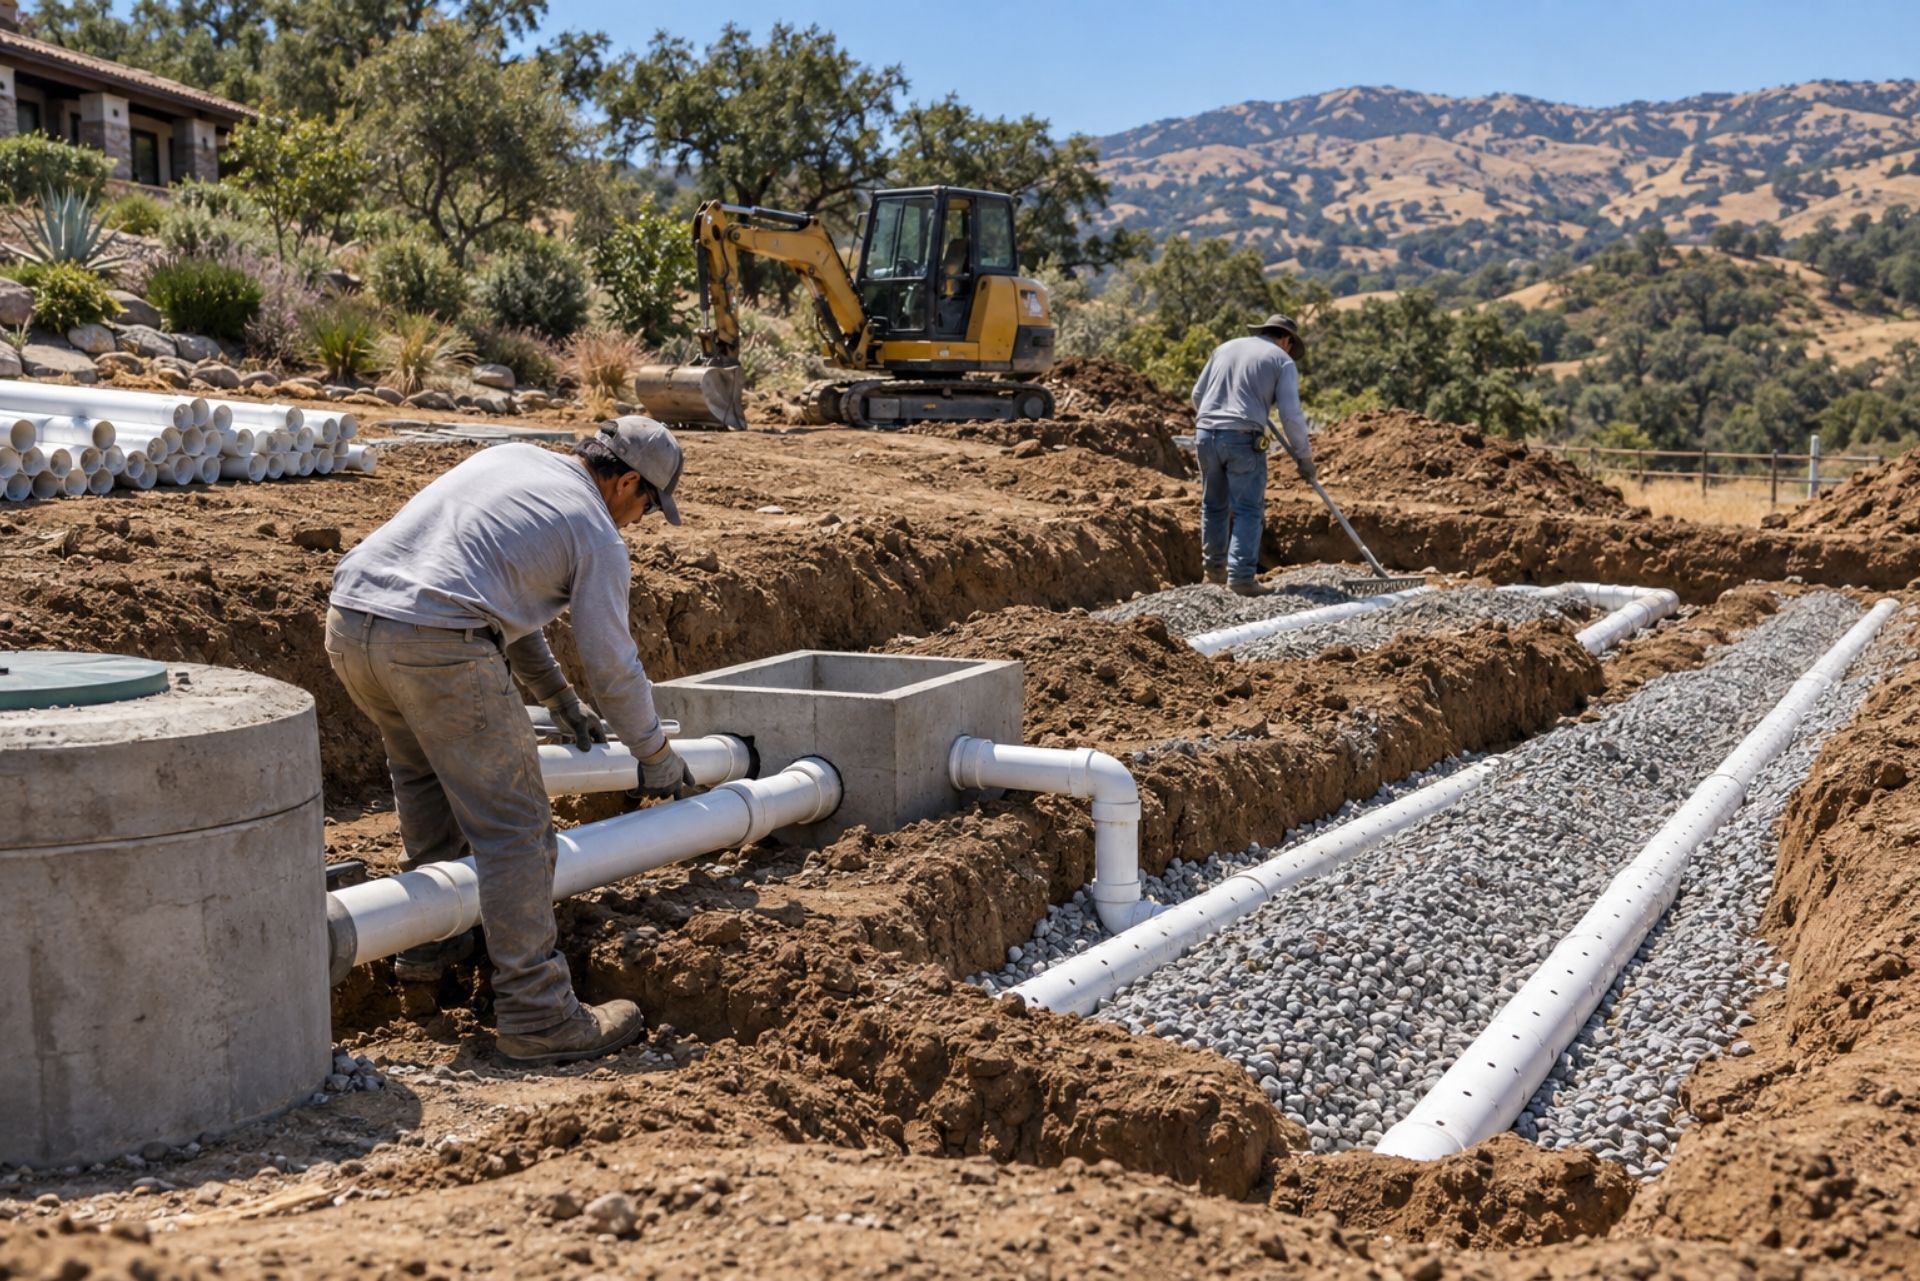
Running a septic business in California means working with heavy equipment, handling waste, digging near utility lines, and operating in one of the most regulation-heavy states in the country. One bad day on a job site - a ruptured sewer line, a contaminated well, a worker injury - can cost you six figures before your lawyer even picks up the phone. The right insurance coverage isn't just a box to check for your CSLB license; it's the difference between surviving a claim and shutting your doors. This guide to septic contractor insurance in California breaks down every policy you need, from
general liability and pollution coverage to pump truck insurance, workers' comp, and the bond requirements tied to your C-42 license. Whether you're a one-truck operation pumping residential tanks or a crew running full installations, the coverage gaps in your current policy could be more dangerous than the trenches you dig.
Essential Insurance Policies for California Septic Businesses
Septic work touches property, people, and the environment in ways that most contracting trades don't. A standard contractor's insurance package will leave you exposed unless it's been specifically tailored for the risks you actually face. Three policies form the foundation of any California septic contractor's coverage.
General Liability for Third-Party Property Damage
General liability is your first line of defense when something goes wrong on someone else's property. Think about the scenarios you deal with weekly: your excavator clips a neighbor's retaining wall, a pump hose fitting fails and sprays effluent across a homeowner's patio, or a customer trips over equipment on the job site. Each of these triggers a general liability claim.
For California septic contractors, policies typically start around $1 million per occurrence with a $2 million aggregate. Carriers will want to know whether you do installation work, pump-outs only, or both, because installation involves trenching and backfill that dramatically increase your exposure. If you subcontract any portion of a job, make sure your policy includes coverage for subcontractor liability, or require subs to carry their own GL and name you as an additional insured.
Professional Liability and Errors & Omissions
This one catches a lot of septic contractors off guard. If you design a system, recommend a tank size, or advise a homeowner on drain field placement, you're providing professional services. When that advice turns out to be wrong - maybe the perc test was misread, or the system you recommended fails within a year - the homeowner's attorney won't file under your general liability. They'll file a professional liability claim.
E&O coverage protects you when your expertise is the thing being questioned. It's especially relevant for contractors who handle engineering-adjacent tasks like system design or who sign off on inspection reports. Even if you think you're "just pumping tanks," review your contracts: if there's any advisory language in your scope of work, you have E&O exposure.
Pollution Liability and Environmental Coverage
Here's where septic contractors face risks that most other trades simply don't. Standard general liability policies almost universally exclude pollution events. That means if a tank you installed leaks and contaminates a neighbor's well, or a pump truck spills waste during transport, your GL policy won't pay a dime.
Septic-specific
pollution liability coverage in California
runs roughly $165 to $625 per month, depending on your revenue, crew size, and the types of jobs you take on. California's environmental regulations are aggressive, and the state doesn't hesitate to pursue cleanup costs against the responsible contractor. A single groundwater contamination event can generate remediation bills in the hundreds of thousands. This is not optional coverage for septic work - it's essential.
By: Patrick Caruso
President of Caruso Insurance Services
California State Licensing and Bond Requirements
California ties your ability to work directly to your compliance status. Letting a bond lapse or skipping workers' comp doesn't just risk a fine; it can cost you your license entirely.
CSLB Contractor License Bond (C-42 Classification)
Every C-42 sanitation system contractor in California must carry a contractor license bond filed with the CSLB. This bond protects the public - not you - if you fail to perform contracted work or violate licensing laws. The current bond requirement is $25,000 for most contractors, though the CSLB can require a higher amount if you've had disciplinary actions or outstanding judgments (https://contractorexamschools.com/classifications/c42-sanitation-system-contractor/). Contractors operating as an LLC must also post an additional $100,000 employee/worker bond (https://www.cslb.ca.gov/about_us/llc.aspx).
The bond itself is not insurance. You pay a premium (usually 1-5% of the bond amount annually, depending on your credit), and if a claim is paid against the bond, you owe the surety company back every dollar. Think of it as a guaranteed line of credit the state holds over your head. Keep your bond current; a lapse triggers automatic license suspension, and reinstatement is neither fast nor cheap.
Workers' Compensation Compliance for California Employers
California has zero tolerance for employers operating without workers' comp. If you have even one employee - including part-time or seasonal crew members - you must carry a workers' compensation policy. The penalties for non-compliance include criminal charges (a misdemeanor), stop-work orders, and civil penalties of $1,500 per employee on the payroll up to a maximum of $100,000 (https://www.worklawyers.com/wage-penalties-california-law/).
Septic work carries a high experience modification rate because of the physical nature of the job: heavy lifting, confined space entry, trenching, and exposure to biological hazards. Your workers' comp premiums will reflect this. Invest in documented safety training, maintain detailed incident logs, and conduct regular toolbox talks. A clean claims history over three to five years can meaningfully reduce your mod rate and save thousands annually.
Protecting Specialized Septic Equipment and Vehicles
Your trucks and equipment are your revenue. A pump truck sitting in a body shop or an excavator stolen from a job site doesn't just cost you the repair or replacement - it costs you every job you can't run while it's down.
Commercial Auto Insurance for Pumper Trucks
Personal auto policies won't cover commercial vehicles, and standard commercial auto may not cover the specialized equipment mounted on a pump truck. You need a policy written for vacuum trucks that covers the chassis, the tank, the pump system, and any hose reels or accessories as a single unit.
California's 2026 vehicle inspection rules add another layer. Under AB 3278, heavy vehicles with a GVWR of 26,001 lbs or more now require 90-day mechanical inspections under the restructured BIT program. Pump trucks below that threshold have shifted to a federal annual inspection cycle, though trucks requiring hazardous materials placards remain on the 90-day schedule regardless of weight. Staying current on inspections isn't just a DOT requirement - carriers may deny claims if your vehicle was out of compliance at the time of an accident.
Inland Marine Coverage for Excavators and Tools
Inland marine insurance covers equipment and tools that move between job sites. Your excavator, trencher, camera inspection systems, and locating equipment are all vulnerable to theft, vandalism, and accidental damage during transport. Standard property insurance only covers items at a fixed location, which is useless for contractors.
Price your inland marine policy based on replacement cost, not actual cash value. A five-year-old mini excavator might be depreciated to $25,000 on paper, but replacing it with a comparable machine in 2026 could run $55,000 or more. Maintain a current equipment schedule with serial numbers, photos, and purchase receipts. Update it every time you buy or sell a piece of equipment.
Risk Management Strategies for Excavation and Installation
Insurance pays claims after something goes wrong. Risk management keeps things from going wrong in the first place, and it directly affects what you pay in premiums.
Mitigating Underground Utility Damage Risks
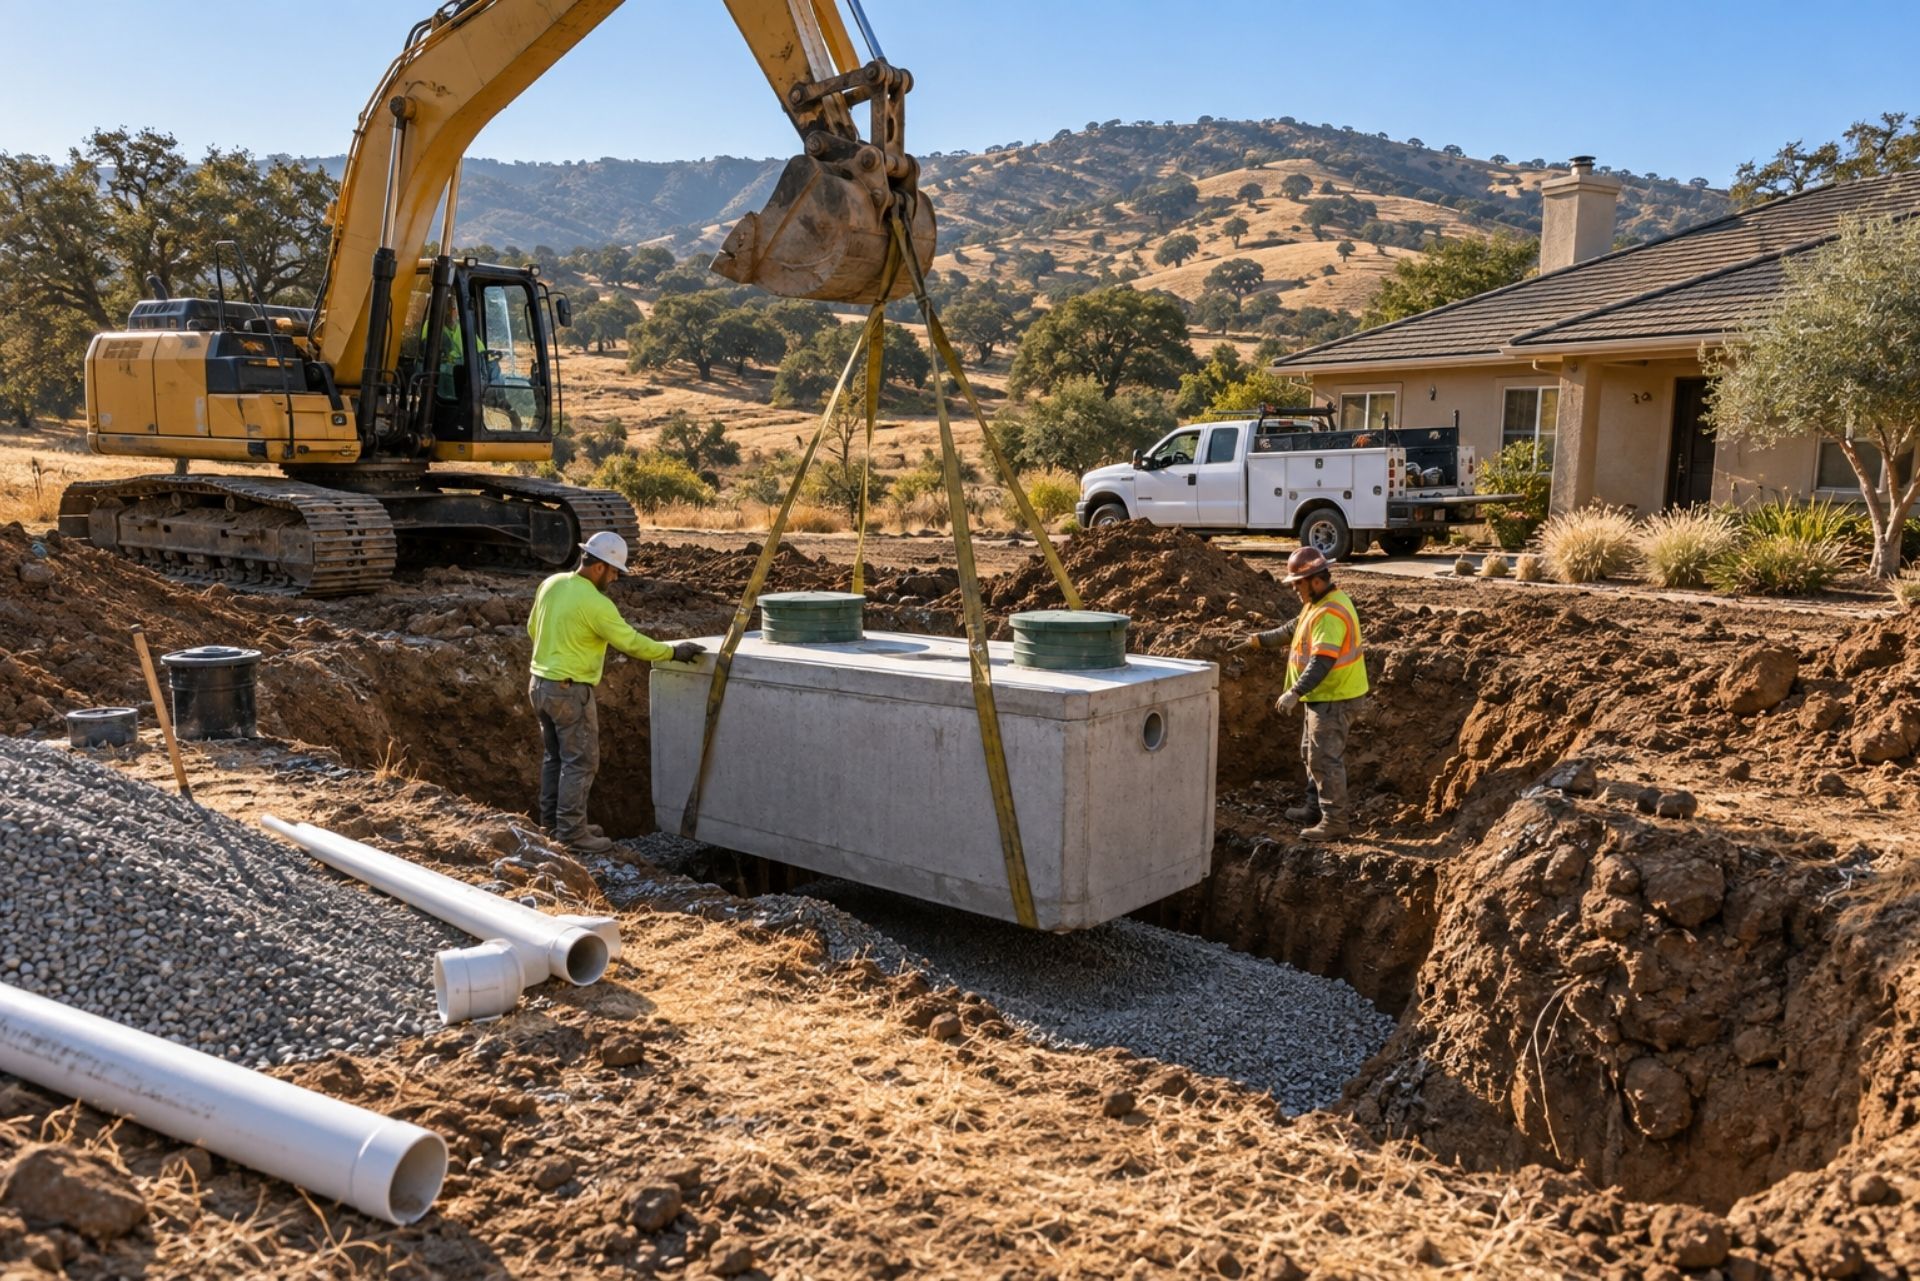
Hitting a gas line or fiber optic cable during excavation is one of the fastest ways to generate a five-figure claim. California law requires you to call 811 at least two working days before any excavation, but smart contractors go further.
- Verify locate marks against available utility maps before breaking ground
- Hand-dig or use vacuum excavation within 24 inches of any marked utility
- Document every locate ticket, mark verification, and any discrepancies with photos and timestamps
- Train every crew member, not just operators, on locate mark identification
A single utility strike can spike your insurance premiums for three to five years. The prevention costs almost nothing by comparison.
Managing Soil Contamination and Leakage Liability
Septic system failures create contamination events, and if you installed, repaired, or pumped the system, you're in the liability chain. California's Regional Water Quality Control Boards don't play around with groundwater contamination, and cleanup orders can follow the responsible party for years.
Carry pollution liability with adequate limits - $1 million minimum for most operations, higher if you work near sensitive water sources. Document soil conditions before you start any installation. Take photos of the excavation, note any unusual odors or discoloration, and keep copies of perc test results. If a contamination claim surfaces two years after a job, that documentation is your best defense. Large-scale septic infrastructure projects are growing across the state: the Los Olivos Community Services District alone secured $30 million for a septic-to-sewer conversion, which signals increasing regulatory attention on existing septic systems and the contractors who service them.
Your premiums aren't arbitrary. Carriers price your policy based on measurable risk factors, and understanding them gives you some control over what you pay.
Revenue and payroll are the starting points: a $2 million-a-year operation with eight employees pays more than a solo owner-operator doing $300,000. The types of work you perform matter enormously. Pump-out-only operations are significantly cheaper to insure than contractors doing full installations with excavation. Your claims history over the past five years is the single biggest factor after revenue. Carriers check your loss runs the way lenders check your credit score, and a pattern of claims - even small ones - will push you into higher-risk tiers.
Geography plays a role too. Contractors working in areas with high water tables, earthquake zones, or near coastal wetlands face higher pollution liability premiums. Your fleet age and maintenance records affect commercial auto rates. And your safety program, if it's documented and consistently followed, can earn premium credits from many carriers.
Get quotes from at least three brokers who specialize in contractor insurance, and make sure they understand septic-specific risks. A generalist broker will miss coverage gaps that a specialist catches immediately.
When a claim happens, your response in the first 48 hours shapes the outcome. Report incidents to your carrier immediately, even if you're not sure whether the damage will exceed your deductible. Late reporting is one of the most common reasons carriers reduce or deny payouts.
Document everything at the scene: photos, witness contact information, a written timeline of events, and any communications with the property owner. Don't admit fault or make promises about repairs. Let your adjuster handle negotiations. If a pollution event is involved, contact your environmental liability carrier separately, since it's a different policy with different reporting requirements.
At renewal time, come prepared. Bring updated equipment schedules, current employee counts, revenue projections, and documentation of any safety improvements you've made. If you've gone claim-free, ask your broker to shop your policy. Loyalty to a single carrier rarely rewards you the way competitive quotes do.
Your claims history follows you through industry databases, much like a CLUE report tracks homeowner claims. A clean record is one of your most valuable business assets, so protect it through prevention, proper documentation, and prompt reporting when incidents do occur. The right insurance program for a California septic contractor isn't a single policy - it's a coordinated set of coverages that match the specific risks you take on every day. Build it with a specialist broker, review it annually, and treat your safety program as seriously as your bottom line.
ABOUT THE AUTHOR:
PATRICK CARUSO
I’m Patrick Caruso, founder of Caruso Insurance, and I have spent more than 25 years helping families, contractors, and small businesses across Southern California make confident insurance decisions. I focus on explaining coverage in clear terms, comparing multiple carriers, and supporting clients with steady communication so they feel secure with each step. My goal is to provide dependable guidance, simple answers, and a smooth process for anyone who needs personal or business insurance.
Contact Us
Service that stays with you.
Our team helps simplify insurance decisions for families and businesses. We focus on clear explanations, fast responses, and dependable service. You can count on us for help with coverage questions, updates, and long-term support.
Coverage that keeps you secure
Reliable Protection for Everyday Life
Home insurance helps protect your house, personal belongings, and liability risks. We explain coverage options clearly so you know what your policy includes.
Auto insurance provides protection for accidents, liability, and vehicle damage. We help you compare options so you can choose coverage that fits your driving needs.
Motorcycle insurance provides coverage for riders and their bikes. We help you select options that match how and where you ride.
RV insurance supports protection for motorhomes and recreational vehicles. Coverage applies during travel and while parked.
Coverage Built for Contractors and Trades
Support that keeps your work moving.
General Liability Insurance
General liability insurance helps protect contractors from injury and property damage claims. It supports jobsite requirements and contracts.
Workers Compensation
Workers compensation insurance helps protect employees injured while working. It also supports compliance with state requirements.
Commercial Auto Insurance
Commercial auto insurance provides coverage for work vehicles used on jobsites. It helps protect drivers and company vehicles.
Contractor Insurance
Contractor insurance supports trades and service professionals across Southern California. It helps protect tools, equipment, and daily operations.
Cyber Liability Insurance
Cyber liability insurance helps protect business data and customer information. It supports recovery from digital incidents.
Commercial Property Insurance
Commercial property insurance helps protect offices, shops, and equipment. It supports recovery after covered damage.
Coverage Built for Specialized Work
Support for high-risk and service-driven industries.
Simple Steps Supported by Steady Guidance
A Clear Path to Coverage
Trusted by Clients Across Southern California
Clear service backed by real experiences.
Answers to Common Questions.
Clear explanations to guide your decisions.
How do I know which insurance policy is right for me?
We compare coverage options from multiple carriers to help you see differences in protection and price. You can review clear details and ask questions so you understand what each policy covers. Our team guides you step by step so you feel sure about your decision.
What factors affect my auto insurance premium?
Auto insurance premiums are influenced by your driving history, age, location, vehicle type, and coverage choices. A clean driving record and good safety features can help lower costs. We review these factors with you and help find coverage that fits your budget and needs.
Does homeowners insurance cover all types of damage?
Standard homeowners insurance protects your structure, personal belongings, liability, and additional living expenses in many cases. However, it usually does not include flood or earthquake damage without separate policies. We help you decide if extra coverage is right for your home and location.
Can I update my policy or get certificates online?
Yes. You can submit requests for policy changes and certificates through our online service form at any time. Our team processes those requests quickly and confirms updates once complete so you have the documents you need.
Do I need separate insurance for business risks like EPLI or E&O?
Yes. General liability and workers compensation cover many business risks but do not protect against all exposures. For example, Employment Practices Liability Insurance (EPLI) covers claims like wrongful termination or discrimination, and Errors & Omissions (E&O) covers claims based on mistakes in professional services. We help you identify which extra policies your business may need.
What happens if I need to file a claim?
If you need to file a claim, we guide you through the process and help you contact the insurance carrier. We explain what information you should provide, answer your questions, and stay available while the carrier reviews your claim. This support helps you move forward with confidence.
Contact Us